Signals
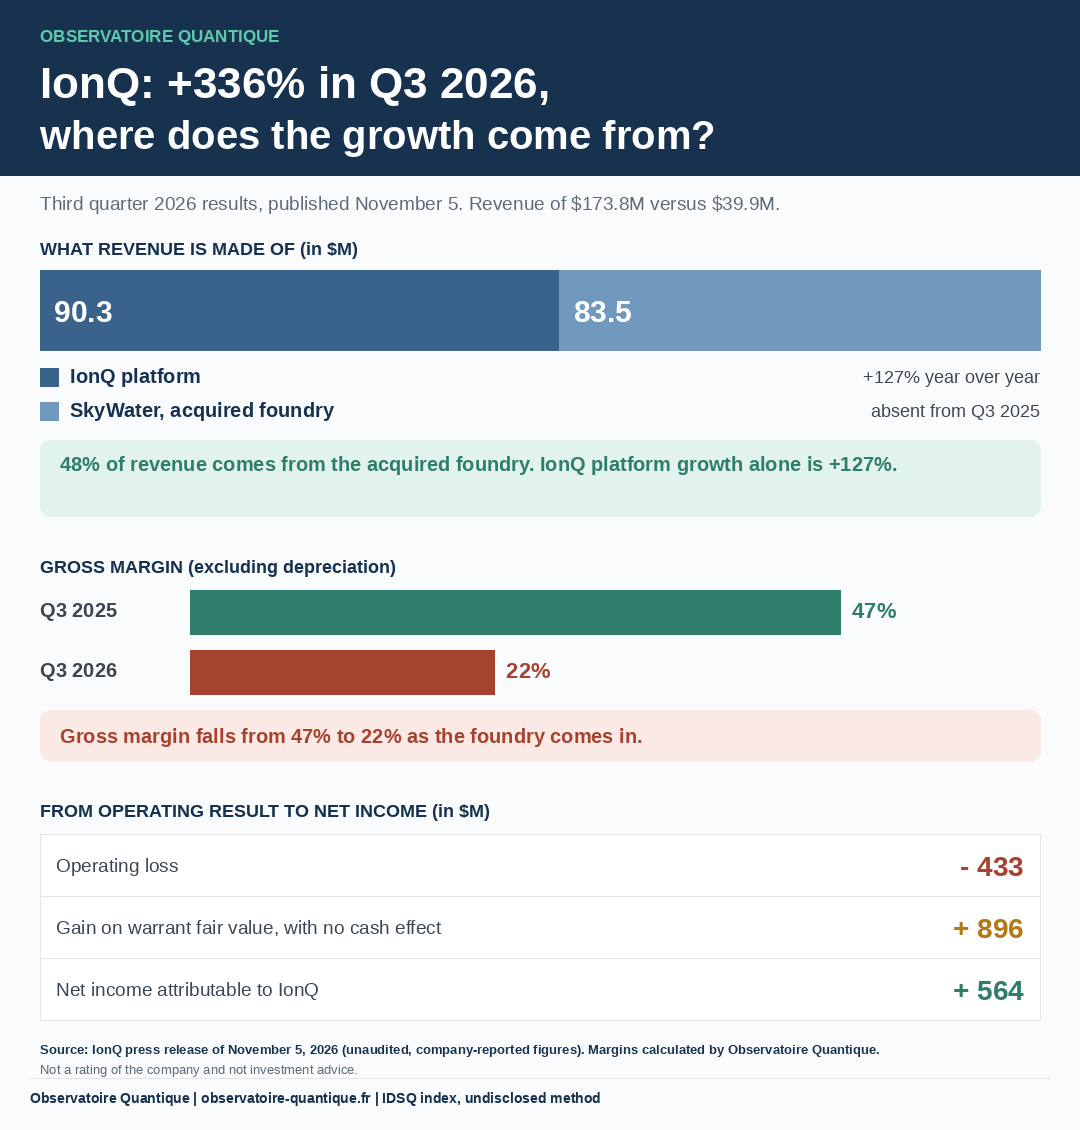
IonQ: +336% in Q3 2026, with 48% of revenue coming from the acquired foundry
IonQ published on November 5, 2026 revenue of $173.8 million for the third quarter, versus $39.9 million a year earlier (+336%). The company raises its full-year guidance to $505 to $515 million, which implies $186 to $196 million in the fourth quarter. It reports $1.2 billion in remaining performance obligations, which include SkyWater and contracts not yet funded.
Revenue is made up of $90.3 million for the IonQ platform (+127% year over year) and $83.5 million for SkyWater, the acquired foundry. SkyWater accounts for 48% of the total and was not in the Q3 2025 accounts. It has been consolidated only since the closing on July 31, two months, so the +336% growth is largely external, the organic reading being the platform (+127%). It has been consolidated only since the closing on July 31, two months, so the +336% growth is largely external, the organic reading being the platform (+127%). Cost of revenue, excluding depreciation, rises from 53% to 78% of revenue: gross margin calculated this way falls from about 47% to about 22%.
The operating loss is $433 million ($169 million a year earlier) and adjusted EBITDA is minus $133.6 million. Net income attributable to IonQ is nevertheless plus $564 million, driven by an $896 million gain on the fair value of warrants, with no cash effect. Cash and investments are $1.7 billion at September 30, or $3.7 billion including the $2.0 billion equity offering of October 16.
On technology and defense, IonQ says it is the only trapped-ion company in stage C of DARPA's benchmarking programme (potential value up to $300 million), and announces that a Superion 256 will be the first on-premise quantum computer at NVIDIA's quantum research center. Through SkyWater, IonQ also manufactures superconducting platforms for customers such as Qolab and D-Wave: its business is no longer limited to trapped ions.
Why this is a strong signal: one of the sector's most visible players is changing nature, from quantum computer builder to industrial group and foundry. This echoes our note "Valuation Doesn't Tell the Whole Story": strong growth and positive net income can coexist with a falling gross margin and a rising operating loss.